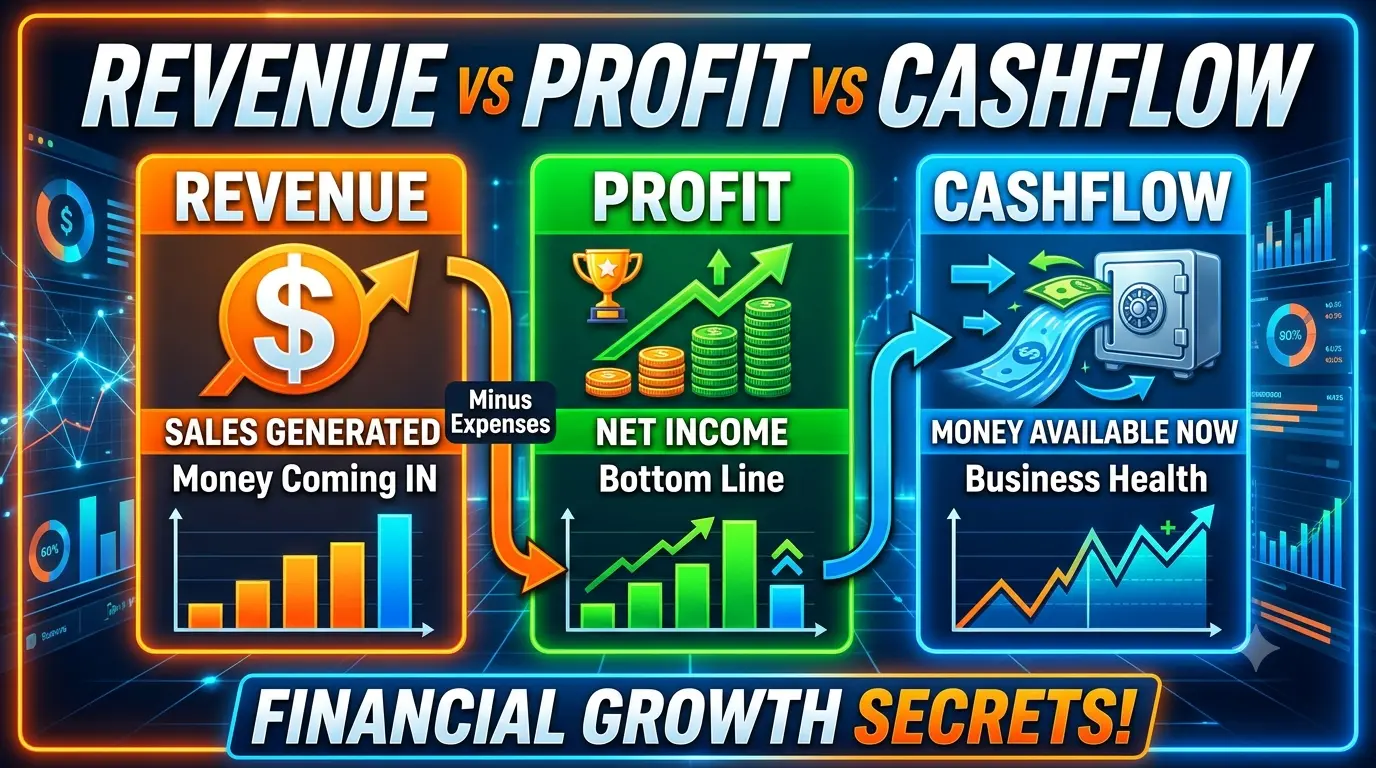
Revenue vs profit vs cash flow are three important financial terms used to understand a company’s performance. Although they are related, they do not mean the same thing.A company may generate high revenue but earn a small profit. It may also report a profit while generating a different amount of cash from its business operations. To understand these differences, let us look at the FY2025–26 consolidated financial results of Tata Motors Limited, which now primarily represents the commercial vehicle business following the demerger.
What Is Revenue ?
Revenue is the money a company earns from selling its products or services before deducting its expenses.
For example, when a vehicle manufacturer sells trucks and buses to customers, the money earned from those sales contributes to its revenue.
Revenue formula
Revenue = Sales of goods and services
Revenue shows the scale of a company’s business, but it does not tell us how much money the company keeps after paying its expenses.
What Is Profit ?
Profit is the amount left after deducting relevant expenses from revenue and accounting for other income, costs, taxes and other items, depending on the type of profit being measured.
There are different types of profit, including operating profit, profit before tax and net profit.
Net profit formula
Net Profit = Total Income − Total Expenses, including applicable taxes
Net profit helps investors understand how much a company earned after accounting for its expenses and taxes. However, profit does not necessarily mean the same amount of cash entered the company’s bank accounts during that period.
What Is Cash Flow ?
Cash flow measures the movement of cash into and out of a business.
Cash comes into a company through activities such as collecting payments from customers, while cash goes out through payments to suppliers, employees, lenders and other parties.
Cash flow is divided into three main categories:
- Operating cash flow: Cash generated or used by the company’s main business operations.
- Investing cash flow: Cash spent on or received from assets and investments.
- Financing cash flow: Cash received from or paid to lenders and shareholders, including borrowings, repayments and dividends.
Operating cash flow is particularly useful because it helps investors understand how much cash the business generates from its regular operations.
Real Example: Tata Motors’ Revenue, Profit and Cash Flow in FY26
According to Tata Motors Limited’s FY2025–26 Integrated Annual Report, the company reported the following consolidated figures for the financial year ended March 31, 2026.
| Financial measure | FY26 amount |
|---|---|
| Revenue from operations | ₹83,855 crore |
| Operating profit | ₹8,306 crore |
| Profit before tax | ₹4,663 crore |
| Profit after tax (net profit) | ₹3,030 crore |
| Cash from operating activities | ₹14,981 crore |
| Free cash flow (Auto) | ₹12,438 crore |
Source: Tata Motors Limited, Integrated Annual Report FY2025–26. Figures are consolidated and reported in ₹ crore.
1. Revenue: ₹83,855 Crore
Tata Motors generated ₹83,855 crore in revenue from operations during FY26.
This figure represents the company’s revenue from its operations. It is not the amount the company earned as profit, because running a vehicle manufacturing business involves costs such as raw materials, employee salaries, manufacturing, research and development, and other expenses.
2. Profit: ₹3,030 Crore
Tata Motors reported a consolidated profit after tax of ₹3,030 crore in FY26.
This means that after accounting for the relevant income, expenses, exceptional items and taxes, the company reported ₹3,030 crore as profit for the year.
Its net profit was much lower than its revenue because revenue and profit measure different things.
The company’s net profit was approximately 3.6% of revenue. This is calculated by dividing ₹3,030 crore by ₹83,855 crore and multiplying by 100.
3. Cash Flow: ₹14,981 Crore From Operations
Tata Motors generated ₹14,981 crore in cash from operating activities during FY26.
This figure was higher than its reported net profit of ₹3,030 crore. The annual report explains that operating cash flow includes adjustments for non-cash items, changes in working capital and direct tax payments.
For example, accounting expenses such as depreciation can reduce reported profit without representing an equivalent cash payment in the same period. Changes in the timing of customer collections and payments to suppliers can also affect operating cash flow.
Therefore, operating cash flow and net profit can differ significantly. The difference does not automatically mean that the company has a financial problem.
Tata Motors also reported free cash flow (Auto) of ₹12,438 crore. This is a separate measure calculated using the company’s stated definition, which adjusts operating cash flow for specified investment and financing-related items.
Revenue vs Profit vs Cash Flow Main Differences
| Basis | Revenue | Profit | Cash flow |
|---|---|---|---|
| What it measures | Income from operations | Earnings after relevant costs | Movement of cash |
| Main purpose | Shows business scale | Shows profitability | Shows cash generation and usage |
| Expenses deducted? | Not generally deducted from revenue | Yes, depending on profit measure | Tracks actual cash movements and adjustments |
| Can it be positive when another measure is weak? | Yes | Yes | Yes |
| Tata Motors FY26 example | ₹83,855 crore | ₹3,030 crore net profit | ₹14,981 crore operating cash flow |
Which Is More Important for Investors?
None of these three measures should be analysed in isolation.
- Revenue: Check whether the company is growing its sales and whether that growth is sustainable.
- Profit: Check whether the company can control costs and convert revenue into earnings.
- Cash flow: Check whether the business generates cash to fund operations, investments, debt repayments and other commitments.
For a better analysis, investors should also examine profit margins, debt, working capital, capital expenditure and trends across multiple financial periods.
A company with rising revenue but falling profit margins may be facing higher costs. A company with positive net profit but weak operating cash flow may need closer examination of customer collections, inventory and working capital.
At The End
Revenue, profit and cash flow explain three different aspects of a company’s financial health. Revenue shows how much a business earns from its operations, profit shows what remains after accounting for relevant costs, and cash flow shows how cash moves through the business.
Tata Motors’ FY26 results illustrate this difference clearly: the company reported ₹83,855 crore in revenue, ₹3,030 crore in net profit and ₹14,981 crore in cash from operating activities. These figures are different because they measure different aspects of financial performance.Investors should study all three together rather than judging a company only by its revenue or net profit.
Frequently Asked Questions
1. What is the main difference between revenue and profit?
Revenue is the income a company earns from selling its products or services. Profit is what remains after accounting for relevant expenses and other items.
2. Can a company have high revenue but low profit?
Yes. High operating costs, interest expenses, depreciation, taxes or other charges can reduce the profit earned from revenue.
3. Can cash flow be higher than net profit?
Yes. Non-cash expenses, changes in working capital and the timing of payments and collections can cause operating cash flow to be higher or lower than net profit.
4. Why is operating cash flow important?
It helps investors understand how much cash a company generates from its main business operations, which can help fund daily activities, investments and financial commitments.
Source
Tata Motors Limited, FY2025–26 Integrated Annual Report
Financial figures are based on the company’s published annual report.